



What’s inflation?
Why do groceries, gas, and other everyday expenses cost more than they used to? The answer may be inflation, when the prices of goods and services rise over time. Learn what causes inflation, how it can affect your finances and retirement goals, and ways to help lessen its impact on your wallet.
[Updated article; original published date August 2, 2022]
Key takeaways
|
What’s the rate of inflation?
A common measure of U.S. inflation is tracked by the Consumer Price Index (CPI). It shows the change in the price of a basket of everyday goods and services, such as housing, food, gas, and healthcare. The chart below shows how inflation rates have changed, on average, over the past decade.
U.S. annual rate of inflation (2016-2026)
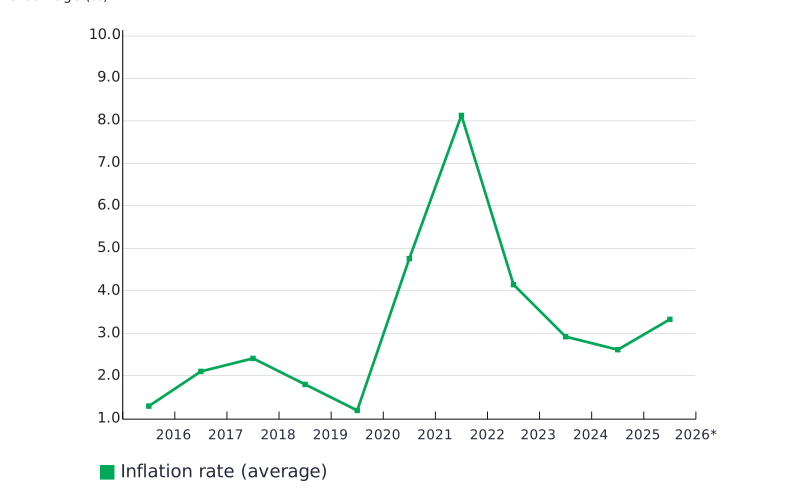
*For the six months ended June 30, 2026. Source: Average Inflation Rates in the United States, excludes data from 9/25 through 12/25 due to the government shutdown.
What causes inflation?
Inflation can rise or fall for many reasons, including changes in consumer demand, energy prices, supply chain disruptions, and interest rates. For example, inflation surged to an average annual rate of 8.0% in 2022. During the pandemic, product shortages, shipping delays, and labor constraints caused consumer demand to outpace supply, and prices quickly rose across the economy. Inflation gradually fell as production and distribution issues eased and higher U.S. interest rates helped curb consumer spending and slow price increases.
What’s purchasing power?
Inflation affects your purchasing power, which is how much you can buy with a certain amount of money. When prices stay the same, your purchasing power remains stable. When prices rise because of inflation, your purchasing power declines because the same amount of money buys fewer goods and services.
What’s shrinkflation?
Have you ever opened a carton of ice cream or a bag of chips and felt like there was less inside than there used to be? That's an example shrinkflation, or product downsizing. Shrinkflation occurs when companies reduce the size, quantity, or amount of a product, without changing the price. You’ll get less product for the same amount of money. While shrinkflation may be less noticeable than a price increase, it can have the same effect by reducing your purchasing power.
How does inflation affect your wallet?
The table below is an example of how inflation can affect your finances. Assuming a 3% annual inflation rate, something that costs $100 today could cost about $181 in 20 years. At the same time, the purchasing power of $100 would decline to about $55, meaning the same amount of money would buy fewer goods and services than it does today. As a result, you may need to save more, invest differently, or adjust your budget to maintain the same standard of living over time.
You can use this calculator to see how different inflation rates can affect the purchasing power of money.
Year | Cost of everyday items | Purchasing power |
|---|---|---|
Today | $100 | $100 |
After 5 years | $116 | $86 |
After 10 years | $134 | $74 |
After 20 years | $181 | $55 |
Source: U.S. Inflation Calculator: Future Cost and Lost Buying Power. For illustrative purposes only, assuming a 3% annual rate of inflation. Amounts rounded to the nearest dollar. Individual circumstances vary and may not be reflective of your situation.
How can inflation affect your retirement savings?
Inflation can reduce the value of your retirement savings over time because future expenses may cost more than they do today. If your savings and investments don't grow at a rate that keeps up with inflation, your purchasing power may decline, meaning you may be able to afford less in retirement. This is especially important because retirement can last decades.
What can you do about inflation?
While you can’t control rising prices, you can control many of the financial decisions you make. Below are four ways to help manage inflation's impact on your wallet.
1 Look for opportunities to save
Consider ways you can reduce your daily expenses. Small changes, such as cooking at home more often, using store brands, reducing energy use, and avoiding impulse purchases, can help you keep more in your wallet.
2 Find ways to boost your income
Consider asking for a raise, pursuing a promotion, taking on a side gig, or selling items you no longer need. Even modest increases in income can help offset rising costs.
3 Keep saving and investing for retirement
By consistently saving and investing for retirement, you give your money the chance to grow through compounding, which may outpace inflation. This can help preserve your purchasing power so that your savings can support the lifestyle you want in retirement. Also, consider:
- Making annual catch-up contributions to your retirement account, if you’re eligible
- Automatically increasing your contribution rate each year, if your plan allows
- Diversifying your portfolio to help reduce investment risk
- Reviewing your portfolio with a financial professional to make sure you’re aligned with your savings goals, risk tolerance, and anticipated retirement date
4 Focus on improving your financial wellness
Taking steps to improve your overall financial well-being may help you weather periods of high inflation and reduce unnecessary spending. Consider creating a budget, paying down high-interest debt, building an emergency fund, or setting short-term financial goals to make them more manageable.
When inflation rises, focus on what you can control
Understanding how inflation affects your purchasing power can help you make more informed choices. Start by focusing on the things you can control, such as your spending habits, savings rate, and retirement contributions. Remember that making small, consistent changes can make it easier to navigate rising prices and stay on track with your long-term financial goals.
Important disclosures
Important disclosures
The content of this document is for general information only and is believed to be accurate and reliable as of the posting date, but may be subject to change. It is not intended to provide investment, tax, plan design, or legal advice. Please consult your own independent advisor as to any investment, tax, or legal statements made.
MGR1016266010163 10/26 RET-1799850